Money can bring up questions about security, freedom, family and the kind of work you want to do. Reflecting on those questions may be useful. Your bank balance, however, is not a measure of your worth, spiritual development or honesty with yourself.
Financial difficulty can involve low pay, job loss, illness, caring responsibilities and costs you cannot simply think away. A compassionate review starts with those realities—not the assumption that fear or “bad energy” caused the problem.
Separate three questions
What is happening?
Use amounts, dates and terms: income received, bills due and necessary expenses.
What does it bring up?
Name feelings or expectations without treating them as proof of a hidden cause.
What matters to me?
Consider stability, time, care, independence or other priorities in your circumstances.
What could I do next?
Choose a modest action, request for information or source of appropriate support.
The Consumer Financial Protection Bureau’s money-motivations resources recognize that financial choices involve personal goals, social influences and financial reality. Reflection can help you describe a goal; it does not manufacture the resources needed to meet it.
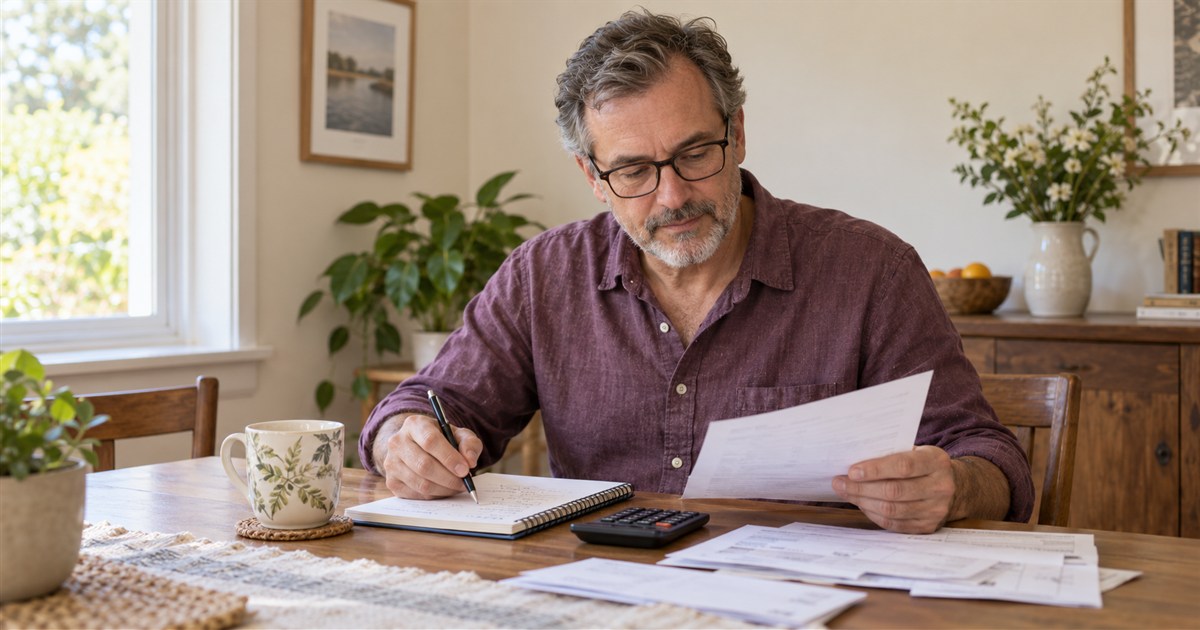
Try a no-blame money check-in
Choose a manageable part of the situation rather than attempting to solve everything in one sitting. Keep account numbers, passwords and private documents out of any spiritual reading or public discussion.
- Write one fact. For example, “My next invoice is due after the rent payment,” rather than “I am bad with money.”
- Name one feeling. “I am worried” is enough. You do not need to redefine a real concern as false evidence.
- Identify one priority. Choose something specific to you, such as predictable working hours or understanding a fee.
- List an unanswered question. “What does this contract actually pay, after charges?”
- Choose one action. Gather a document, ask for written terms or find suitable support.
This exercise is for organizing a conversation, not prescribing debt repayment, investments or tax treatment. Those questions may need qualified advice based on your location and full circumstances.
Use records alongside reflection
Feelings about spending can be important, but they do not replace dates and amounts. A cash-flow problem may involve when money arrives as well as how much arrives. Avoid budgeting around an unconfirmed offer, a psychic prediction or a hoped-for future payment.
The CFPB Your Money, Your Goals toolkit includes an income tracker, spending tracker, bill calendar and cash-flow budgeting resources. Choose the tool that matches your immediate question rather than collecting worksheets you do not need.
| Reflection question | Checkable information | Useful action |
|---|---|---|
| “I want more stability.” | Actual pay arrangements, hours and income dates. | Compare written terms before accepting a role. |
| “I feel pressured to buy training.” | Full cost, curriculum and cancellation terms. | Pause and request missing details. |
| “I am avoiding the numbers.” | One recent statement or bill. | Review a manageable item with suitable support. |
| “I want work that fits my values.” | Real duties, requirements and working conditions. | Use a job comparison worksheet. |
For a psychic practice, distinguish revenue from take-home income
A headline session rate does not describe your entire working day. Ask about platform charges, refunds, unpaid waiting and preparation, payment timing and any costs you must cover. Request written terms instead of using another reader’s income story as your budget.
Use the applications and work-planning FAQ to prepare questions. The job comparison worksheet helps assess actual options without treating symbolism as an earnings forecast.
Keep spiritual reflection out of financial promises
You may use a personal ritual or affirmation to remind yourself of a goal. Do not treat it as proof that money is coming, that a debt will disappear or that someone deserves hardship. A reader should not promise wealth or demand payment to unblock income.
If you consult a reader, keep the question reflective: “What assumptions am I making about this change?” Avoid sharing access credentials or seeking instructions about investments, legal obligations or medical costs. Review the reply with the record, sort, check and choose process.
Ask for the kind of support you actually need
You can ask a trusted person to sit with you while you organize records, request clarification from a provider or seek qualified financial, legal or tax support. Check an adviser’s role, credentials, fees and any conflicts of interest before committing.
If money worries are affecting daily life, emotional support can be useful alongside practical help. It should not come with a claim that your distress proves spiritual failure.
Frequently asked questions
1. Does financial hardship reveal my true character?
No. A bank balance does not measure character, worth or spiritual development.
2. Can beliefs alone create financial security?
Reflection may help clarify goals, but it does not guarantee income or remove practical constraints.
3. What is a no-blame money check-in?
It separates facts, feelings, priorities and unanswered questions before choosing a manageable action.
4. Should I call every money worry false evidence?
No. Concerns about actual bills, income or housing can be real. Look at the facts without dismissing the concern.
5. What records are useful to start with?
Choose a relevant income record, bill, statement or written contract. Start with a manageable part of the situation.
6. Should I share account details with a psychic?
No. Do not share passwords, account-access information or unnecessary private financial documents in a reading.
7. Can a reading predict my future earnings reliably?
Do not build a budget around a psychic prediction. Use actual income and confirmed written arrangements.
8. Is revenue the same as take-home income?
No. Charges and business costs can affect what remains, and a session rate does not describe all your working time.
9. What should I ask a reading platform?
Request written information about payment calculation, charges, refunds, scheduling and payment timing.
10. Do affirmations guarantee money?
No. An affirmation can be a personal reminder, not a guarantee of income or debt relief.
11. Should I pay to unblock my income spiritually?
Pause when a seller promises wealth or makes fear-based demands for payment. Seek an independent perspective.
12. Where can I find ordinary tracking tools?
The CFPB Your Money, Your Goals toolkit offers income, spending, bill-calendar and cash-flow resources.
13. Can this article tell me how to repay debts?
No. It is a general reflection guide, not an individualized debt, investment, legal or tax plan.
14. How do I choose appropriate professional support?
Check the person’s role, credentials, fees and conflicts of interest. Make sure their expertise fits your question.
15. What is a useful first action?
Choose one checkable step, such as gathering a record or asking for written terms. It need not solve the entire situation.
The discussion about money reflecting our beliefs and values is very insightful. It’s true that our spending habits often mirror our deeper values and family history. This perspective encourages a more mindful approach to financial management.
I appreciate the call to ‘know thyself’ in relation to finances. Self-awareness is crucial in any endeavor, and understanding our relationship with money is no different. Asking sincere questions about our needs can lead to a more balanced life.
The article makes a compelling case for rethinking our relationship with money. Understanding the psychological and emotional dimensions of finances can be transformative. The idea that money acts as a mirror reflecting our deepest concerns is quite profound.
The concept of money as an energy that uncovers our innermost fears and aspirations is quite intriguing. Recognizing these underlying emotions can help in transforming our financial habits and lead to greater freedom and authenticity.
It’s interesting to see money framed as a shamanic territory. The analogy helps to highlight the psychological and emotional impact that financial stress can have on us. Reframing our thoughts about money could indeed open up new opportunities.